A benefits expert on managing specialty drug costs, GLP-1 demand, and employee health strategy
For HR directors and benefits managers, this open enrollment season is arriving with a weight unlike any in recent memory.
Rising premiums, surging specialty drug costs, and growing employee demand for coverage of glucagon-like peptide-1 (GLP-1) medications are forcing employer plan sponsors to make structural decisions – not just incremental adjustments – about how their benefits programs are designed.
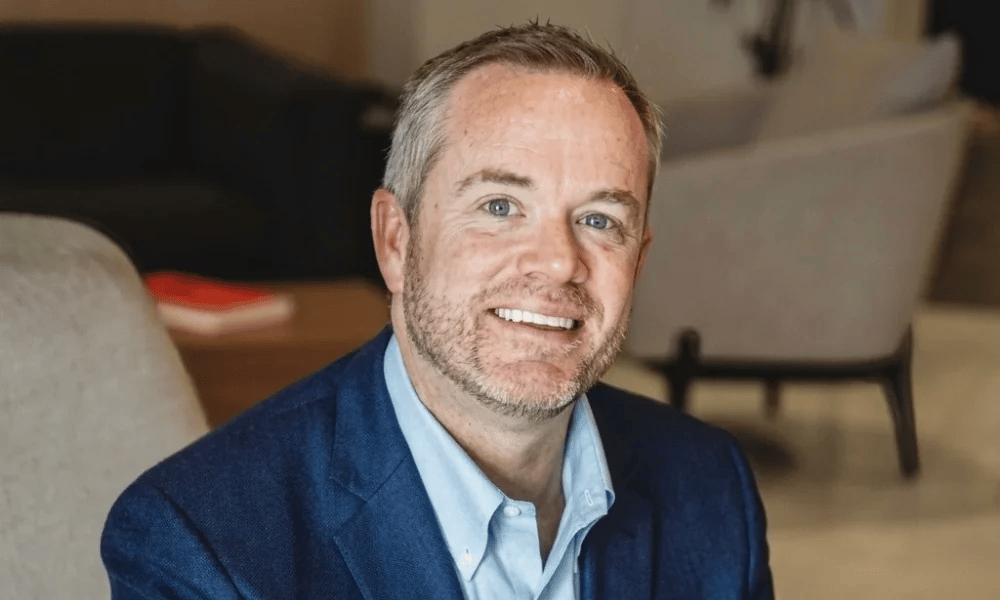
Wes Cowen, National Practice Leader for Employee Benefits at OneDigital, whose firm advises employer clients across the United States, did not sugarcoat the challenges in an interview with HRD America as part of a series of interviews on the state of open enrollment.
"The last two years have probably been the most challenging that I've seen in my entire career," said Cowen, who has spent 25 years in the industry, including 15 years at two large national insurance carriers. "We've really spent a good amount of the last 12 months helping [employers] to prepare for this."
Cowen is clear that recalibrating plans only when renewal figures land is no longer sufficient.
Stop absorbing costs and start redirecting them
One of Cowen's sharpest observations concerns the instinct of many employers to shield employees entirely from rising healthcare costs. While that impulse is understandable, particularly at a time when grocery and gas prices are also stretching household budgets, he argues it is neither financially sustainable nor strategically sound.
"Employers can't fully shield their employees from rising costs, but they can limit how much lands on them," Cowen said. "While employers can't make cost pressure disappear, they can decide where it lands."
Cowen's team is working with employers across a spectrum of funding strategies, from fully insured and level-funded arrangements to self-funded plans and emerging individual coverage health reimbursement arrangement (ICHRA) structures, now increasingly referred to as CHOICE. Alongside funding strategy, the conversations span pharmacy benefit manager (PBM) transparency reviews, narrow pharmacy and provider networks, and shifts of high-cost services such as infusion therapy to lower-cost sites of care.
The breadth of options can itself be paralyzing, Cowen acknowledged.
"There's definitely not a one-size-fits-all approach. We really focus on how to personalize [strategy] to an employer, the employer's own population, the risk profile that exists within that population, and also some local market dynamics."
For HR leaders looking to benchmark their organization's approach against peers, SHRM's annual employee benefits survey and the Kaiser Family Foundation's employer health benefits report offer useful context on how U.S. employers are responding to the current cost environment.
The GLP-1 decision HR can no longer defer
If there is one benefits decision that is arriving on every HR director's desk right now, it is what to do about GLP-1 medications. Originally developed for diabetes management, drugs in this class are now widely prescribed for weight management and employee demand is rising sharply.
Cowen's advice is to resist binary thinking. Full coverage and blanket exclusion are both blunt instruments. He says that the more durable approach is a structured framework built on clinical criteria, quantity limits, and utilization management - tools that allow employers to provide meaningful coverage for employees who genuinely need these medications while managing plan-level cost exposure.
"It doesn't always have to be all or nothing," Cowen said. "Employers can use clinical criteria, quantity limits, utilization management - there are a number of different ways in which we can help employers to address some of the pain points that exist within their population."
What HR should now expect from their benefits broker
As healthcare cost complexity deepens, Cowen sees a corresponding shift in what employer plan sponsors should demand from the advisors they work with. The annual renewal conversation - carrier quotes, rate comparisons, enrollment logistics - is no longer enough.
What leading brokers now offer, he argues, is continuous population risk intelligence. OneDigital's Impact Studio platform is built to deliver exactly that: real-time analysis of a plan's risk profile that flags emerging cost trends months before they show up in a renewal figure.
"Technology has allowed us to almost have a 24/7 way of analyzing data in the background so that we're constantly able to keep our employers and clients informed of what emerging risk might exist," Cowen said. "And how we can help them to attack that as quickly as possible."
A broker relationship that runs hot only during open enrollment season is likely leaving cost exposure on the table, while the employers Cowen describes as his best clients are already planning for the 2028 plan year while 2027 enrollment is still open. That kind of forward planning requires an advisory relationship and data infrastructure that operates year-round.
Cowen also noted that employees themselves are increasingly being equipped with better decision support tools, helping them understand not just their payroll deduction but how different plan choices affect their out-of-pocket costs.
What 2027 demands from HR leadership
Cowen is clear-eyed about the difficulty of the moment, but he is equally clear that the difficulty is creating an opening for HR leaders willing to move beyond reactive plan management.
"The consultation that our teams are providing to our clients, to employers across America right now, is more valuable today than ever," he said. "It's a very complex system. Having the subject matter expertise in a variety of areas that will help our clients to better understand what their options are really positions us well to provide value."
For HR directors, that observation cuts both ways. The complexity of the current environment is an argument for deeper engagement with benefits strategy - not just delegation to a broker - and for building the internal fluency to evaluate recommendations on pharmacy, funding structure, and plan design with more rigor than the annual renewal cycle typically allows.
The post-midterm policy environment may also bring change. Cowen expressed cautious optimism that policymakers, having heard the breadth of frustration with healthcare costs, would focus on meaningful relief, particularly around pharmacy pricing.
"I think everyone is very hopeful that our leaders will listen to what has really been such a challenging time for people looking to find answers to the healthcare cost crisis," he said. "And that our leaders will be able to work together and focus on ways in which they can deliver some relief."
For HR leaders heading into 2027, that relief may or may not arrive on a policy level. What is within their control is how well-prepared their organizations are when it does – or does not.