M3 Insurance’s Jason Nordby on why captive models are giving HR leaders an edge on health costs
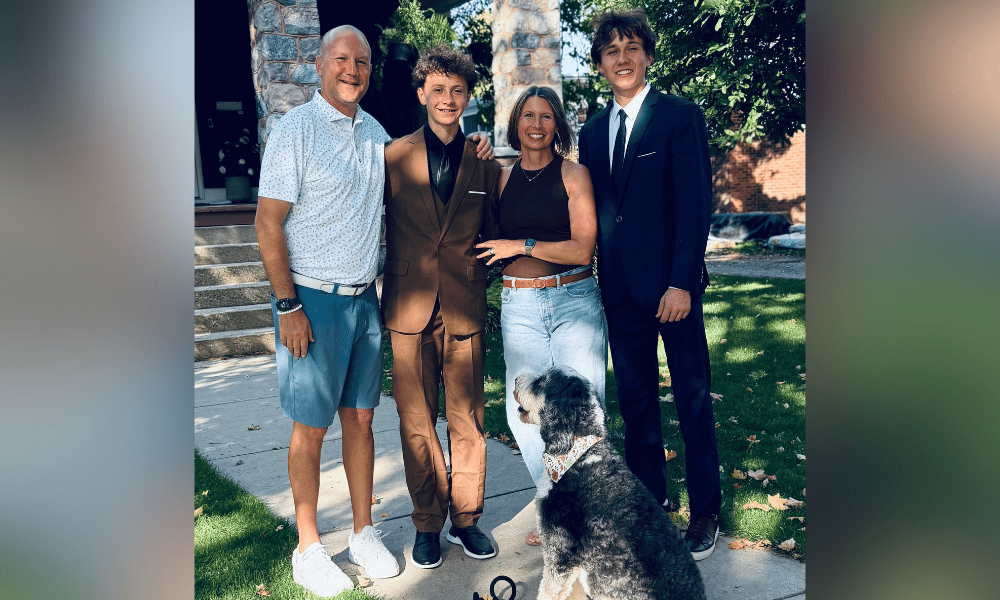
For most HR directors and CFOs, the annual health insurance renewal arrives like an unwelcome bill with no receipt. Costs go up. Explanations are vague and the options on offer look broadly the same as they did the year before. Jason Nordby (pictured), Director of Captives at M3 Insurance, has spent the better part of two decades watching that cycle repeat and he is increasingly convinced the answer lies outside the traditional model entirely.
According to internal performance data from M3 Insurance, employer groups enrolled in captive benefit plans are outperforming their fully insured and self-funded counterparts by approximately 7 percentage points. On a $1 million annual health spend for a 100-person organization, the compounding effect of that differential over several years represents significant savings and it is widening as the broader market continues to correct.
How he got here
Nordby did not arrive at captive benefits strategy in a straight line. He graduated from college, took a job within a healthcare system, and was studying for his master’s degree in the evenings when a chance introduction changed his trajectory. A nurse colleague had a brother who was an executive at UnitedHealthcare, one of the largest health insurers in the United States. Rather than write a thesis paper, Nordby spent time working across UnitedHealthcare’s departments as a practical substitute. When it was over, they hired him.
He moved into provider contracting and relations, leading that function at a smaller insurer before the company was acquired. He then joined a coalition of employers working to reduce the cost of healthcare and it was there, calling on brokers to bring their clients into the fold, that his path to M3 began. The broker he was calling on was in the process of becoming President of M3 Insurance, and he recruited Nordby with a straightforward pitch: join a small firm, grow it together.
When Nordby arrived, M3 had around 50 employees. It now has north of 500.
Why the traditional insurance model is failing employers
For HR leaders tasked with balancing competitive benefits packages against rising costs, the current environment is particularly punishing. A post-COVID double effect has created what Nordby describes as a hard insurance market: during the pandemic, widespread underutilization of healthcare led insurers to under-project future claims, while healthcare systems simultaneously raised prices to recover lost revenue. The correction playing out over the past 18 to 24 months has been steep for organizations in traditional fully insured and self-funded arrangements.
But the structural problem, he argues, predates COVID. For years, mid-market employer groups that consistently ran well effectively generating a surplus for their insurer were still pooled with other groups and subjected to market-rate increases. When they finally experienced a difficult year, the protection they believed they had bought rarely materialized.
“I would see these groups that made money for the insurance company four years in a row and still taking nominal increases, thinking that when they have that bad year, they were going to be protected,” Nordby said. “But when they would have that bad year, they would still get the massive increases.”
Captive models offer a genuine alternative. They give employers the transparency and data access of self-funding, visibility into what is actually driving claims, and the ability to act on it while sharing large claim risk across a cleaner, more purposefully assembled group of like-minded organizations. The volatility that makes individual self-funding difficult for mid-market employers is dramatically reduced. And because captive groups sit outside the traditional market’s pooling logic, they are largely insulated from the dynamics currently driving costs up elsewhere.
“Because the captive model itself is creating its own unique, cleaner risk pool, it is not susceptible to the market dynamics that are happening in that hard market,” Nordby said.
The drug cost conversation HR needs to be having
Prescription drug spend is one of the most visible and most mismanaged cost drivers on any employer plan. When Nordby started at M3 in 2003, encountering a high-cost specialty drug on a client’s plan was extraordinary. Today, he walks into every new client conversation expecting to find several.
For HR leaders, the instinct is often to manage this cost by tightening plan design or shifting more of the burden onto employees. Nordby argues that a more effective lever is choosing the right pharmacy benefit manager (PBM). Transparent, pass-through PBMs leverage patient assistance programs, manufacturer support, and international drug sourcing to dramatically reduce the cost of high-cost specialty medications. An approximately $100,000 annual drug cost can often be significantly reduced or effectively eliminated while the employee continues receiving their medication without interruption.
The human dimension matters as much as the financial one.
“That poor employee who’s on that high-cost drug is going from maxing their plan out-of-pocket costs in the first month of the plan year to potentially having no out-of-pocket cost,” Nordby said. “And what do you think that does for culture and for attraction and retention?”
Cancer compounds the challenge. At a presentation to the Wisconsin Manufacturers and Commerce Association during the summer of 2026, attended by approximately 35 senior human resources professionals, Nordby asked the room to raise their hand if they did not currently have an active cancer case within their plan. Not a single hand went up.
Managing cancer well requires specialist vendor partners with deep expertise across cancer types. General healthcare providers, however respected, typically lack the granularity to differentiate treatment protocols across subtypes, which leads to wasted care, worse outcomes, and higher plan costs.
What HR leaders should expect from their benefits advisor
The broker relationship, Nordby believes, has fundamentally changed and HR leaders should be demanding more from it. The era of an annual renewal conversation followed by 12 months of silence is over. What a good benefits advisor offers today is year-round analysis: tracking claims trends, identifying emerging cost drivers, and benchmarking the plan against competitors in the same labor market.
That last piece is where M3’s AI platform, BrokerPRO, comes in. Nordby describes it as a tool that surfaces, for the first time, how an employer’s benefit plans compare to those of neighboring organizations competing for the same talent.
“Most groups don’t really know how their benefit plans stack up to the neighboring benefit plans,” he said. “If we can show them where they’re falling short, where they’re maybe spending too much money and right-size that they are going to be able to deploy their resources to the right places, which is ultimately going to help them attract and retain employees.”
The test, Nordby suggests, is simple: is your benefits advisor showing you what is driving your costs and helping you fix it or are they showing up once a year with a renewal number?
What the next few years hold
Nordby is optimistic about the direction of travel, for organizations willing to move. Business owners, CFOs, and HR leaders, he says, have reached a breaking point with traditional models. Appetite is building for alternatives, captives, direct primary care, virtual care, mental health solutions. At the same time, private equity consolidation in brokerage is squeezing internal resources at larger advisory firms, which means plan sponsors working with those firms may be receiving less proactive support than they once did.
“We’ve had very high-level executive consultants who 10 years ago would have never considered leaving their organization and coming to M3,” Nordby said. “They’ve seen the M3 model, how we are not driven by revenue goals to some shareholders that have nothing to do with our business. We are reinvesting our revenue into the appropriate resources to better serve our clients.”
For HR leaders evaluating their advisory relationships, that question of where a firm’s priorities actually lie is a reasonable place to start.