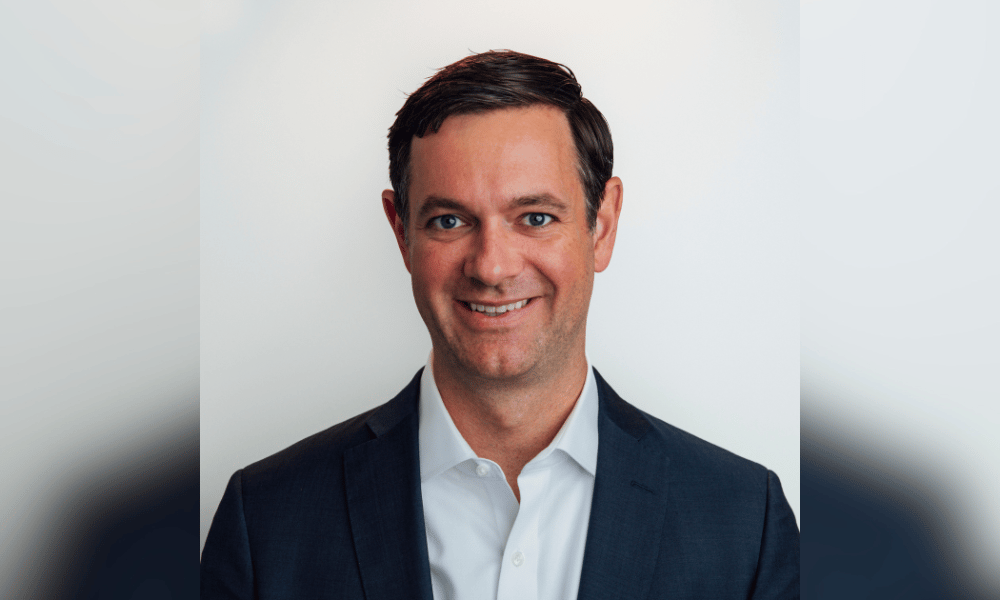
Jack Hooper of Take Command says the defined contribution model could free employers from managing health plans entirely
As HR directors face another year of double-digit health plan renewal increases, the promise of defined contribution healthcare has an obvious appeal: set a budget, hand employees the money, and let them buy their own coverage.
But the question has always been whether the market infrastructure to support that model is mature enough to deliver on the promise.
Jack Hooper, CEO of Take Command, a Dallas-based platform that administers Individual Coverage Health Reimbursement Arrangements (ICHRAs) for employers, thinks it is and he has been making that case directly to the Trump administration.
A few weeks ago, Hooper met with Dr. Mehmet Oz and senior officials at the Centers for Medicare & Medicaid Services (CMS) to discuss the future of what the administration is now calling "CHOICE arrangements," its rebrand of the ICHRA model.
"I'm very convinced that at some point we'll look back in America and say it all flipped over to this model," he told HRD America. "If it takes three years, five years, 10 years - I don't know - but it'll get there."
The cost pressure driving interest
The timing matters for HR decision-makers. As HRD has reported, 42 percent of employers reported health plan premium increases of 10 percent or more at their most recent renewal, according to Gallagher's 2026 Benefits Benchmarks Report, with pharmacy costs emerging as the most significant and least controllable driver. Under a traditional group plan, those cost increases land on the employer's balance sheet year after year.
Under an ICHRA model, the employer's liability is fixed. The organization contributes a defined monthly amount per employee - differentiated by role, employment status, or geography if needed - and employees use that allowance to purchase individual coverage on the Affordable Care Act (ACA) marketplace. If premiums rise in the individual market, the employer's contribution stays the same unless they choose to adjust it.
"They don't want to be managing a health plan," Hooper said of the employers he works with. "And it's odd that in the US, that's how we've evolved our system. If they can get out of it but still take care of their employees and provide a benefit, they'll jump out right away."
The ACA dependency HR leaders need to understand
There is a critical caveat that any HR leader evaluating ICHRA needs to understand. The affordability and quality of CHOICE arrangements is entirely dependent on a healthy ACA marketplace and the ACA marketplace is under pressure. As HRD has reported, the expiration of enhanced ACA premium subsidies is already reshaping which workers seek employer coverage and on what terms, with individual market enrollment falling 2.8 percent in the 12 months to June 30, 2026.
Hooper raised this tension directly with Dr. Oz. The administration has spent years seeking to weaken the ACA marketplace - the same marketplace on which CHOICE arrangements depend.
"He was like, 'Hey look, we were trying to get rid of the ACA. Now we think we need it,'" Hooper recalled. "So we're going to make it as best we can."
He also made the case for restoring Cost-Sharing Reduction (CSR) payments - federal subsidies that help lower-income employees cover copays and deductibles, which the first Trump administration cut. Research from both sides of the aisle, he said, now shows that eliminating CSR payments increases the federal deficit through silver loading, and restoring them now appears in Trump's own healthcare plan.
The practical implication for employers is that ICHRA works best in markets with a robust individual market. Before recommending the model to the C-suite, benefits teams need to assess individual plan availability and quality in the geographies where their employees live, not assume that national adoption trends translate to their workforce's specific locations.
What CHOICE means for the employee experience
Hooper is candid that navigating from a handful of group plan options to hundreds of individual market plans is genuinely disorienting for employees and that the employer's role in that transition matters enormously.
Take Command's approach is to guide employees through a structured intake process, gathering information on family size, medical needs, preferred physicians, and prescriptions before recommending a specific plan. Hooper draws a deliberate parallel to the shift from defined-benefit pensions to 401(k)s - a transition that also required significant employee education and communication before it became the default.
"We try to help employees use that choice to their advantage," he said, "and not just feel overwhelmed by 'I was confused before and now there's even more options.'"
For HR teams, that means the communications and onboarding burden does not disappear under an ICHRA model - it shifts. Rather than communicating a handful of group plan options at open enrollment, HR leaders need to ensure employees understand how to shop for individual coverage, what their allowance covers, and who to call when problems arise. And as HRD has reported, rising pharmacy costs are already straining employees' ability to afford care under existing plans, making benefits communication and plan design more consequential than ever.
Is CHOICE right for your organization?
Hooper's advice is to treat ICHRA as a third option alongside fully insured and level-funded or self-funded plans - not a wholesale replacement for either.
For organizations with employees concentrated in strong individual markets, stable headcount, and appetite for a multi-year transition, the defined contribution model offers genuine cost predictability and the prospect of exiting the health plan management business entirely.
For those with complex workforces, significant lower-wage populations, or employees in thin individual markets, the model warrants careful actuarial analysis before any recommendation reaches the board.
"I'm not a partisan group," Hooper said. "If it makes the most sense to go with a choice arrangement, we're going to help you get there. If it doesn't, we'll tell you that too."