Most employees never invest their HSA balances - and HR has the power to change that
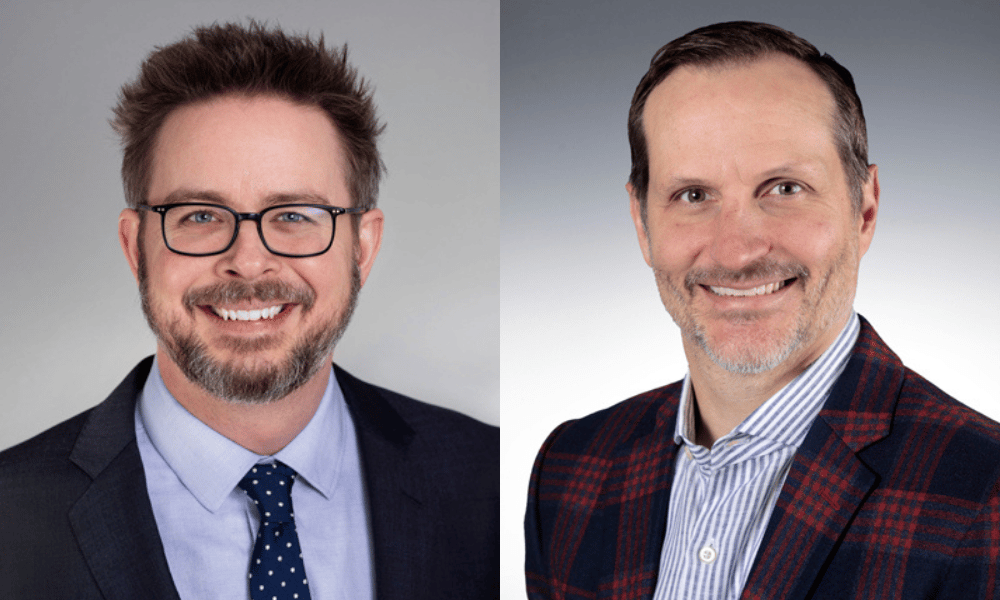
For most employees, the health savings account their employer helped set up is little more than a place to park money before a doctor’s visit. Hans Leida thinks that is one of the most consequential missed opportunities in American workplace benefits today.
Leida is a principal and consulting actuary at Milliman, where he has spent his career working with health insurers, large employers, and government entities on the true cost of healthcare risk in the United States. His message for HR leaders is that the way most employers administer HSAs is leaving employees financially exposed and the fix is largely within HR’s control.
According to the September 2026 release of the Milliman Health Trend Guidelines, healthcare cost inflation is currently running at 10.3 percent year over year, measured on claims incurred through April 2026 and paid through June 2026.
With the Consumer Price Index sitting at 3.7 percent, healthcare inflation is running at approximately 280 percent the rate of broader price increases in the U.S. economy. But according to Devenir’s 2026 Midyear HSA Research Report, published October 13, 2026, only about 11 percent of all HSA holders - approximately 4.7 million of the 42.6 million accounts in the U.S. market - held invested assets as of June 30, 2026.
“Brokers, advisors, employers all have an opportunity to do that,” Leida told Insurance Business Benefits U.S. “And also to make sure they’re offering HSA bank options to their employees that have additional investment options.”
The retirement cost employers aren’t talking about
The scale of the problem becomes clear when retirement healthcare costs are quantified. The 2026 Milliman Retiree Health Cost Index, published by Milliman actuaries Robert Schmidt and Eric Walters in June 2026, projects that a healthy 65-year-old couple retiring in 2026 needs approximately $418,000 in savings to cover lifetime healthcare costs - an increase of approximately $28,000 to $30,000 from 2025 estimates. For a male retiree on original Medicare plus Medigap Plan G plus Part D, the required savings figure is $199,000; for a female retiree on the same pathway, it is $219,000.
Those numbers sit largely outside the frame of most employer benefits conversations, which tend to focus on premiums, deductibles, and plan design rather than the long-term retirement healthcare liability employees are accumulating.
“We all need to really try to plan for that retirement that we want while being realistic about what’s needed to accomplish it,” Leida said. “Because otherwise you’re going to end up at your retirement and all that money you had hoped to spend traveling - having the retirement of your dreams - you’re going to end up spending on costs that you didn’t plan for.”
Leida draws a direct parallel to what happened with retirement savings before automatic enrollment and qualified default investment alternatives transformed 401(k) participation. Employers who defaulted employees into savings and invested those savings appropriately changed retirement outcomes at scale. He believes the same logic applies to HSAs - and that HR has the lever.
What HR leaders can act on now
The first and most immediate action, Leida said, is straightforward: audit the HSA bank your organization offers and confirm that it provides investment options beyond a cash sweep account. Many do not. For employees who cannot afford to keep funds invested - those who must draw down their HSA regularly to meet deductibles - a cash account may be the only realistic option. But for employees who can afford to let the balance grow, the choice of HSA administrator determines whether investment is even possible.
Leida said Milliman has been exploring whether purpose-built healthcare inflation-tracking products could serve as a default investment option within employer-sponsored HSA platforms - a direct parallel to the qualified default investment alternative framework under the Pension Protection Act of 2006 that transformed 401(k) outcomes. “We would love for our funds to become a default option for someone, to match really with the liability that they’re taking on,” he said.
Those funds - the Milliman Healthcare Inflation Guard and the Milliman Healthcare Inflation Plus, both launched earlier in 2026 - were developed with Adam Schenck, a partner at Milliman Financial Risk Management, specifically to track healthcare claims trend rather than the medical Consumer Price Index (CPI). The distinction matters because CPI tracks only unit costs, while claims trend also captures utilization shifts and changes in treatment mix over time.
HR leaders can also equip employees with one often-overlooked rule: there is no time limit on reimbursing yourself from an HSA for past eligible medical expenses, provided you retain documentation - an itemized bill, an explanation of benefits, and proof of payment.
Known informally as the shoebox strategy, it allows employees who can afford to pay current medical costs out of pocket to leave HSA funds invested for years and withdraw tax-free against older receipts later. Communicating this during open enrollment costs nothing and could materially improve employee financial outcomes.
The broader picture, Leida warned, is shifting the financial burden onto employees whether employers act or not.
“I’ve seen over the 20 years of my career employers and others really stretching to try to find ways to isolate their employees and their families from these costs as much as they can. But it’s kind of reaching this breaking point where more employers are having to pass more of those costs on to individuals through increased premiums, higher cost sharing, higher deductibles, or reductions in benefits.”
His case for action was ultimately personal.
“What I really wish someone had told me earlier in my career is that signing up for the HSA isn’t just for healthy people who expect not to have healthcare expenses. It is actually a way to get access to another vehicle like a 401(k) that provides significant value to you financially if you have the means and the discipline to make use of it. I am now an HSA investor. I have been for some time, but it took me longer to get there than I wish it had.”
That observation carries a straightforward implication: if one of the country’s leading healthcare actuaries took too long to invest his own HSA, most employees almost certainly have too.