Plan documents are central in tobacco surcharge cases, and HR teams can audit them now
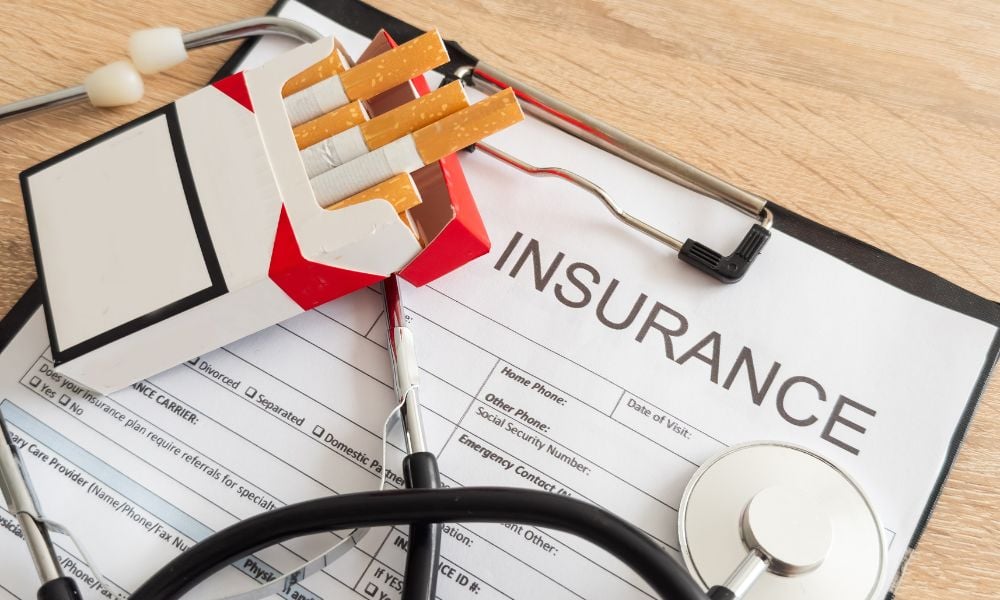
Mondelez International has become the latest large US employer named in a class action over a health plan tobacco surcharge, according to Bloomberg Law. The suit adds to a wave of Employee Retirement Income Security Act (ERISA) litigation that Groom Law Group, a Washington, DC-based employee benefits law firm, counts at more than 80 putative class actions. The plaintiff, court and surcharge amount in the Mondelez case were not confirmed against the court docket for this article.
Other defendants include Progressive, PepsiCo and Compass Group. For HR leaders at organizations that charge tobacco users more for coverage, the cases suggest plan documents are the first thing to review.
What do plaintiffs claim about tobacco surcharges?
The 2013 federal wellness regulations treat a tobacco premium surcharge as a reward under a health-contingent wellness program, according to Thomson Reuters EBIA. Plaintiffs generally allege the program fails the federal wellness rules, most often on the reasonable alternative standard, such as a tobacco cessation course, the notice of that alternative, or the full reward owed to someone who completes it. Many complaints add a fiduciary breach claim.
How are courts ruling on the surcharge cases?
Courts have split. A federal court in the Northern District of Ohio dismissed all five claims against Progressive in March 2026, finding that the company acted as a plan designer and that its summary plan description included a wellness program notice, in a ruling HRD covered in its report on Progressive’s win over the tobacco and vaccine surcharge challenge at the time. The court also held that removing the surcharge going forward satisfies the full reward requirement, with no refund of past surcharges. In 2025, a federal court in Virginia went the other way and denied Performance Food Group’s motion to dismiss, according to Hall Benefits Law.
In the Compass Group case, a Missouri federal judge certified a class, and the ERISA Industry Committee and the American Benefits Council have backed Compass Group’s bid for Eighth Circuit review, PlanSponsor reported. The ERISA Industry Committee has also filed supporting briefs in the Sixth Circuit for Progressive and in the Second Circuit for PepsiCo.
What do the new federal tobacco surcharge FAQs change?
The Departments of Labor, Health and Human Services, and the Treasury issued FAQs About Affordable Care Act and Health Insurance Portability and Accountability Act Implementation Part 74 on August 26, 2026. They address whether a plan must retroactively reimburse a participant for the full plan year when the person completes a reasonable alternative standard partway through it. Thomson Reuters EBIA reported that the preamble to the 2013 regulations indicates the reward must be retroactive but the regulatory text does not clearly require it, and that the FAQs describe enforcement relief on the point.
Mayer Brown said in its analysis that the FAQs reverse a position the Department of Labor (DOL) took in at least two earlier enforcement actions. EBIA also reported that the requirement to disclose the alternative applies when plan materials describe the terms of a health-contingent program, not when they merely mention that one exists. Groom Law Group noted that a program must still give employees enough time to complete the alternative and earn the reward.
The FAQs speak to the timing of the reward and to disclosure. They do not address whether a plan offered an alternative in the first place, so they offer limited help to a program that never did.
Where does the exposure sit for HR teams?
Cases have advanced where enrollment guides and summary plan descriptions did not describe the surcharge, explain the reasonable alternative standard or confirm that a physician’s recommendation would be accommodated, according to Insurance Business reporting on the litigation. Those are documentation gaps that can be corrected before the next plan year. A practical test is to read the enrollment guide and summary plan description as an employee would, checking whether they describe the surcharge, explain the alternative and say a physician’s recommendation will be honored, and whether they state that completing the cessation program earns the full reward. Counsel should review any changes to plan language.
Employers that condition GLP-1 coverage on participation in coaching programs face the same kind of wellness program compliance questions, HRD reported. That review matters more at a time when employers are tightening their grip on benefits spending as healthcare costs surge, because a class action adds legal expense to a budget already under pressure.